Searching "off plan property" usually means you have not yet decided whether paying in stages for a home that does not exist yet is worth the wait. The ranking guides explain the mechanics well: the reservation fee, the exchange deposit, the stamp duty surcharge. What almost none of them explain is how to check, before any money moves, that the specific developer behind a specific project is actually building what it promised.
The standard off-plan sequence, start to finish
The standard UK off-plan sequence runs in four stages (source: investmentproperty.co.uk). You pay a reservation fee to take the unit off the market. You then exchange contracts and pay a further deposit, which is usually twenty to thirty percent of the price. Through the build, nothing further is due. At legal completion, you pay the balance and receive the keys.
Two live 2026 UK schemes show how that sequence plays out in practice (source: vertapropertygroup.co.uk): Paper Yard in Birmingham asks a two thousand pound reservation fee, twenty percent on exchange and eighty percent on completion, with apartments listed from two hundred and forty thousand pounds; ONE Trafford Edge in Manchester starts from one hundred and eighty eight thousand pounds with a thirty eight thousand pound deposit and completion expected in the second quarter of 2027.
A reader weighing that wait against buying something already finished should also read finished home or off-plan: what the trade off really costs, which sets out what you inherit, and what you avoid, on either side of that choice.
What the stamp duty surcharge and the mortgage valuation gap actually cost you
Two costs catch off-plan buyers out because they land later than expected. The first is tax: an investor buying an additional property typically pays a 5% stamp duty surcharge on top of standard rates, and a non-UK-resident buyer usually pays a further 2%, both due at completion rather than at exchange (source: vertapropertygroup.co.uk). Budget for that charge on completion day, not on reservation day.
The second is the mortgage valuation gap. A lender values an off-plan home only once it is finished, not when you exchanged. In May 2026 the average new-build sale price was higher than the average for an existing home (source: vertapropertygroup.co.uk), and if the completion valuation comes in below the price you agreed months earlier, the shortfall is yours to cover in cash. Neither cost shows up in the headline reservation figure, which is exactly why they catch buyers out.
Off-plan in Dubai, and what that comparison leaves out everywhere else
Most UK guides that go beyond the domestic market stop at one comparison: Dubai. Off-plan purchases made up 73% of Dubai Land Department sales in August 2026, and by law every payment sits in a project-specific escrow account the developer can only draw on to build that project (source: vertapropertygroup.co.uk). That escrow structure is a real, structural protection the UK sequence does not have.
What that comparison leaves out is everywhere that is neither the UK nor Dubai. A buyer considering an off-plan purchase on a different coast gets no equivalent legal framework spelled out, and has to find out separately what protection, if any, applies where they are actually buying. Overseas property investment: what the generic guides miss extends this comparison to legal title, tax exposure and financing for destinations outside the UK and Dubai, and buying property in The Gambia: a guide for overseas buyers sets out the wider due-diligence checklist for one specific coast within that comparison.
The verification gap the leading guides leave open
Three of the guides that currently rank for "off plan property" were reviewed for this piece. None of them gives a buyer a concrete way to verify, at the point of deciding, that a specific developer is actually building what it promised.
One guide's entire off-plan section is a list of post teasers, with no process or risk content on the page a visitor actually lands on. A second guide's detailed, numbers-led walkthrough of the UK and Dubai markets reduces developer verification to a single line, telling a reader to check what a developer has "actually delivered, not just what they have launched," and pointing to a separate article rather than describing what that check looks like for a project still under construction. A third guide's due-diligence section amounts to three generic suggestions: inspect other, already-finished homes by the same builder, talk to previous buyers, and consider professional advice. It even flags that due diligence "could be even more important" overseas, without ever saying what that extra, overseas-specific check should be.
None of the three names a specific structural risk a buyer can actually check for before reserving.
The one structural check most guides never mention
One risk sits upstream of all the checks the generic guides do recommend: the handoff between the company that designs a building and the company hired to build it. In the classic model, a design studio draws the plans and a separate contractor builds from them, and scope or quality can drift at exactly that handoff point, well before a buyer ever sees it.
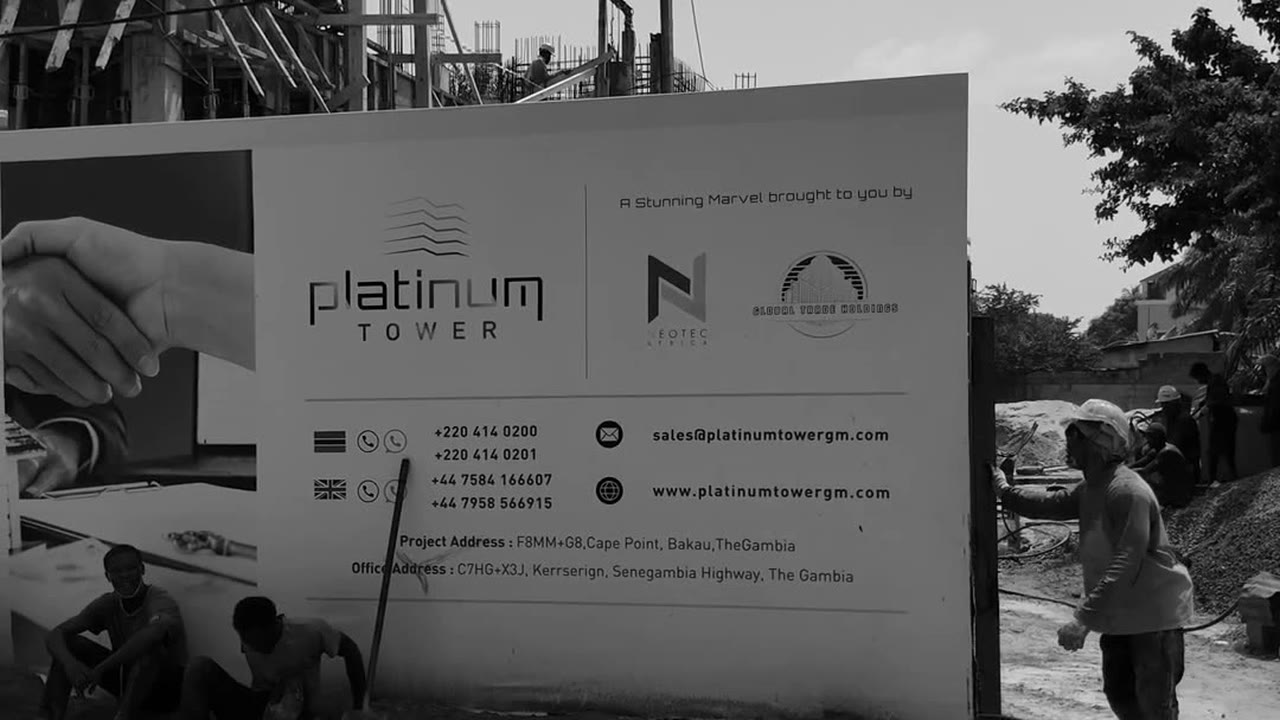
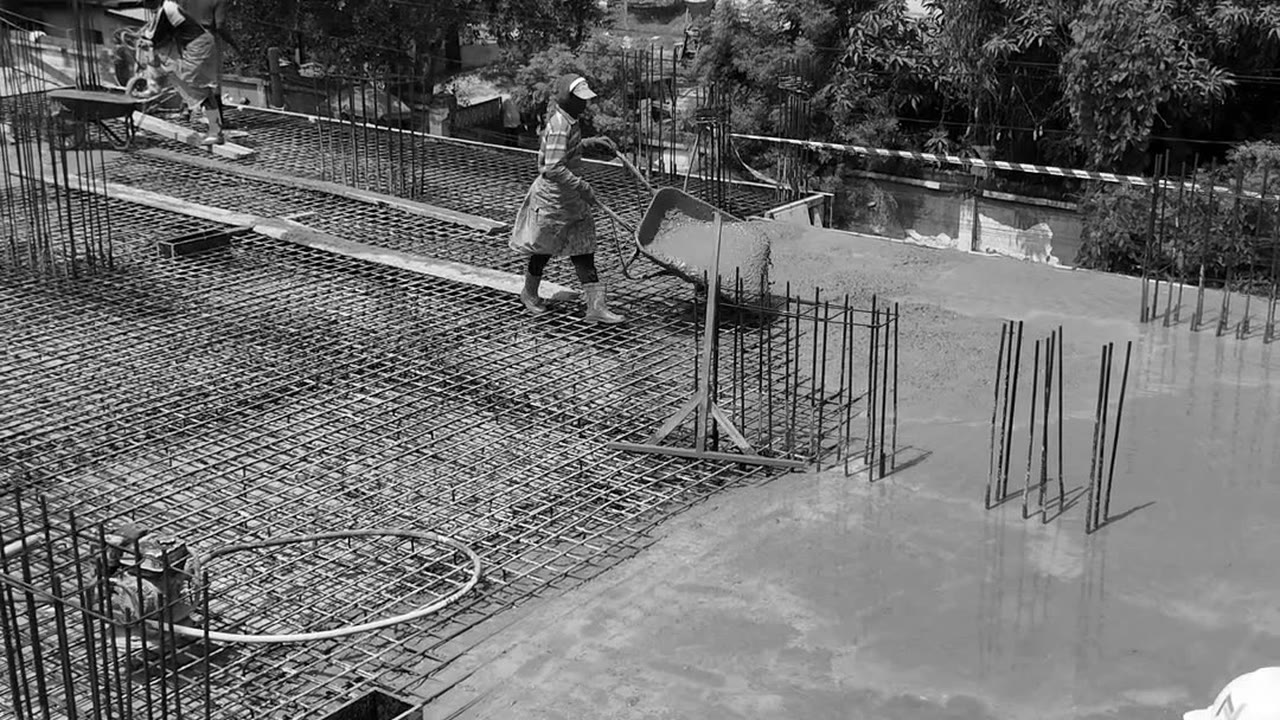
A narrower, checkable alternative is a developer where design and construction sit inside one company, so there is no handoff to drift at. Platinum Tower's own design-build claim, checked line by line, is a working example of what that structure looks like on a live project, and buying off-plan at Platinum Tower sets out what it means in practice for a buyer deciding whether to reserve.
That structure is not a guarantee. It does not mean a finished building will match every render or drawing exactly, and it is not, on its own, proof that construction is progressing on schedule. Treat renders as illustrative rather than as dated proof, and ask any developer, wherever you are buying, for dated evidence of the specific unit or floor you are considering before you commit a deposit.