Type "invest in a real estate" into a search bar and the ranked guides disagree before they even reach returns. One treats every property investment as a fund or trust and never mentions buying a physical unit. Another runs a pooled vehicle gated behind FCA investor accreditation. A third gives buying property abroad three sentences inside a much longer UK-focused page. None of the three shows what it actually looks like to own a specific, individually specified residence directly, without a fund wrapper and without an accreditation test to pass first.
The three ways to invest in real estate, and who can actually access each one
Barclays frames property investing entirely around indirect exposure: open-ended property funds or OEICs, and closed-ended REITs or investment trusts. An investor's return tracks a fund's Net Asset Value or share price, not any one physical address. The page explains the UK tax changes that reduced buy-to-let's appeal, including the 2018 stamp duty surcharge and tapered mortgage interest relief. It never describes what buying or checking a specific unit involves.
Barwood Capital sells the direct alternative, UK regional real estate, but only to investors the FCA classifies as Professional, Certified High Net Worth, or Sophisticated. The firm states it is 100 percent owner-managed, has run 20 funds, and has acquired more than 150 properties. It manages 1.5 billion pounds of gross development value to date, a track record built around pooled vehicles, not a single buyer owning one identifiable residence.
HomeOwners Alliance covers more routes in one place: buy-to-let, property development, holiday lets, buying property abroad, and property funds or REITs. Its UK cost figures are concrete: a buy-to-let deposit of at least 25 percent, or 75,000 pounds on a 300,000 pound property. Since 31 October 2024, an Additional Stamp Duty Rate takes the stamp duty bill on a 300,000 pound purchase to 17,500 pounds, versus 2,500 pounds for a sole residence. Its own section on buying property abroad runs three sentences, naming only "a UK bank that operates in the country" and getting expert advice, with no process for checking what a specific overseas developer is actually building.
Across the three, direct ownership of one specific, identifiable unit is either absent, gated behind accreditation, or covered too briefly to use. That gap is where the rest of this guide sits.
Why real estate works as an investment: income, appreciation and diversification
Real estate earns a return two ways. Rental income is collected while a property is held. Appreciation in the property's value builds over time, but it is only realised when the property is sold or refinanced. Combining both is why HomeOwners Alliance frames 5-7% as a reasonable UK target, a figure that blends yield and expected growth rather than either alone. Property also behaves differently from equities and bonds through a market cycle. That is the diversification case Barwood Capital makes for its own UK fund, positioning regional real estate as a "resilient, diversifying asset class against potentially overvalued asset markets elsewhere."
None of that reasoning changes for a property bought off-plan, with one exception. There is no rental income to collect, and no realised appreciation to count, until construction finishes and the unit is handed over. Everything in the meantime rests on whether the building is progressing the way the developer says it is.
Realistic returns: the 5-7% target and the 2% rule
HomeOwners Alliance's 5-7% target return and its related 2% rule, rent at roughly 2 percent of purchase price signalling a reasonable deal, both assume a finished, let property with a rent roll already running. Neither figure has anything to measure on a unit still under construction, which is exactly the case an off-plan buyer is in.
That gap does not make off-plan property a worse investment on its own. It makes the construction record the thing worth checking before any yield projection. A projected return on a building that is not actually being built as described is not a return at all.
Buying property abroad: the direct-ownership route most guides reduce to a paragraph
Of the three guides reviewed here, only HomeOwners Alliance mentions buying overseas, and only in three sentences recommending a local bank and professional advice. Our own guide to overseas property investment goes further into the mechanics that change by destination: legal title, tax exposure, currency risk, and financing for a buyer earning outside the country where the property sits. Local high street mortgages rarely extend to non-resident buyers, which is why international mortgages and cash purchases dominate this route.
None of the generic guides, UK-focused or overseas, explain how to verify a specific developer's construction claims before money is wired abroad. Invest in The Gambia: what the FDI guides leave out covers one overseas market in that detail: foreign ownership rules, title verification, and the gap between government investment pages built for company formation and a buyer who just wants to own an asset personally.
What direct ownership of a single, specified residence looks like in practice
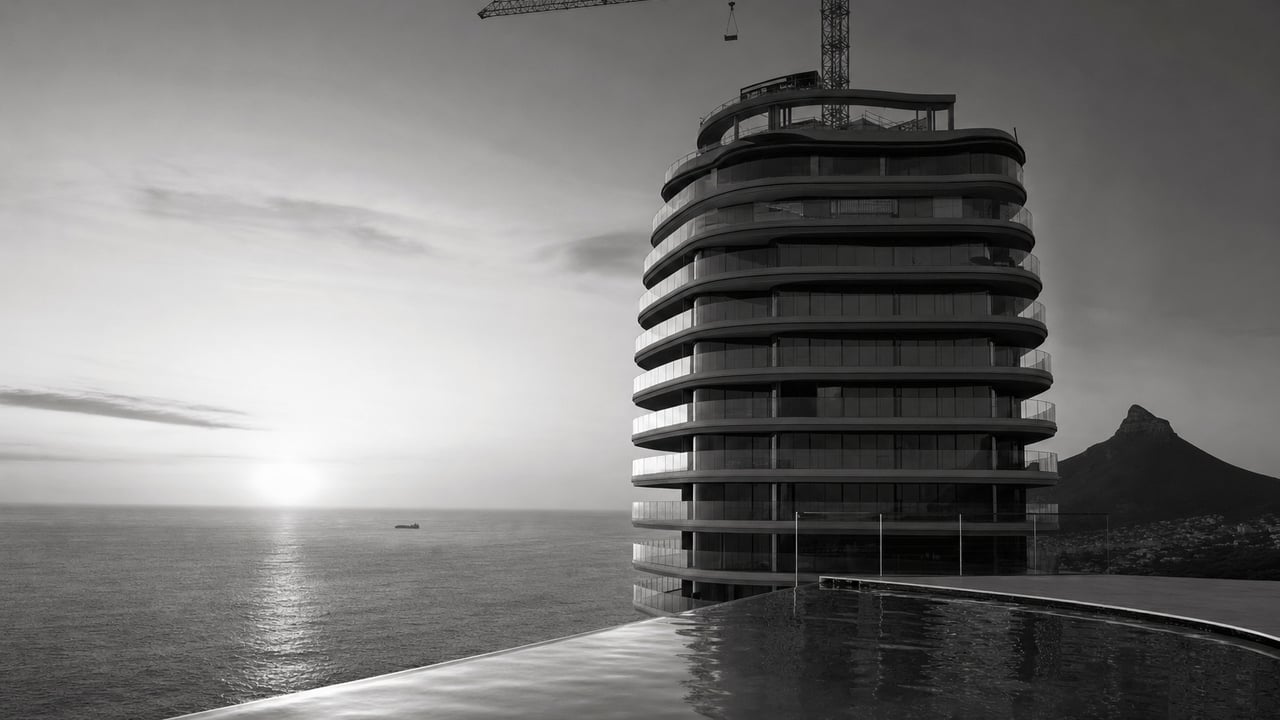
Platinum Tower is a working example of the fourth route none of the three reviewed guides shows. A single developer-builder, Neotec Africa, sells 56 individually specified residences at Cape Point in The Gambia directly to a retail buyer: 18 studios, 18 two-bedroom and 18 three-bedroom apartments, plus 2 penthouses. There is no fund wrapper, no FCA accreditation test, and no share price tracking a Net Asset Value. The buyer owns one named unit, confirmed against the developer's own unit plans, not a stake in a pooled vehicle.
Direct ownership of a physical unit carries its own checks, the ones Barclays and Barwood's pooled structures do not require at all: confirming the title, financing a cross-border purchase, and, for anything still under construction, verifying that the building is actually progressing as described rather than trusting a render. Apartments for sale in Gambia: what the listings leave out covers that last check in one specific overseas market. Finished home or off-plan: what the trade off really costs explains what waiting on construction trades against buying something already built.
Current availability and pricing for Platinum Tower's residences are confirmed directly with the sales team, since neither is published as a fixed figure on this site. Request a virtual presentation to see current construction progress and ask about a specific unit directly.