Most "beginner's guide to real estate investing" results name the same five routes: buy-to-let, flipping, REITs, crowdfunding, and houses in multiple occupation or purpose-built student accommodation. Almost none of them put the entry capital for each route next to the others, so a reader cannot tell, in one place, whether 1,000 dollars or 75,000 pounds is the realistic starting point. This guide does that comparison directly, then covers the one route, off-plan and overseas ownership, that most guides mention only in passing.
Five routes, matched to capital and involvement
Buy-to-let means buying a residential property and renting it out. It is the most active route: finding tenants, handling repairs, and complying with landlord regulation are ongoing responsibilities, not one-off tasks. It is also the most capital-intensive, since UK mortgage lenders typically require a deposit of at least 25 percent.
Flipping means buying a property below market value, renovating it, and reselling it for a profit. It demands active involvement in a renovation budget and a resale timeline, and the capital required covers the purchase, the refurbishment, and the holding costs while the work is underway.
REITs, or Real Estate Investment Trusts, let you buy shares in a company that owns and manages a portfolio of properties. According to Griffin Funding's guide for beginners, shares typically trade for under 100 dollars each, with a sensible starting allocation from around 1,000 dollars. This is the most passive and most liquid route, since REIT shares trade on public markets like any other stock.
Real estate crowdfunding and online investment platforms pool money from many investors into a specific project, often a development or a commercial building. The same Griffin Funding guide puts minimum contributions at 1 to 5,000 dollars. It sits between a REIT and direct ownership: you are backing one named project rather than a diversified portfolio, and your money is usually locked in for longer than a REIT share.
Houses in multiple occupation, and purpose-built student accommodation, are variants of buy-to-let aimed at a specific tenant type, often with higher achievable yield but more intensive management and, for houses in multiple occupation, licensing requirements that vary by local authority.
What a 5 to 7 percent target return actually measures
HomeOwners Alliance frames 5 to 7 percent as a reasonable UK target return, blending rental income with expected price growth rather than quoting either number alone. RW Invest's own guide uses a different rule of thumb for gross rental yield alone: 6 percent is attractive, 8 percent is ideal. Both figures describe a property that is already let and earning rent.
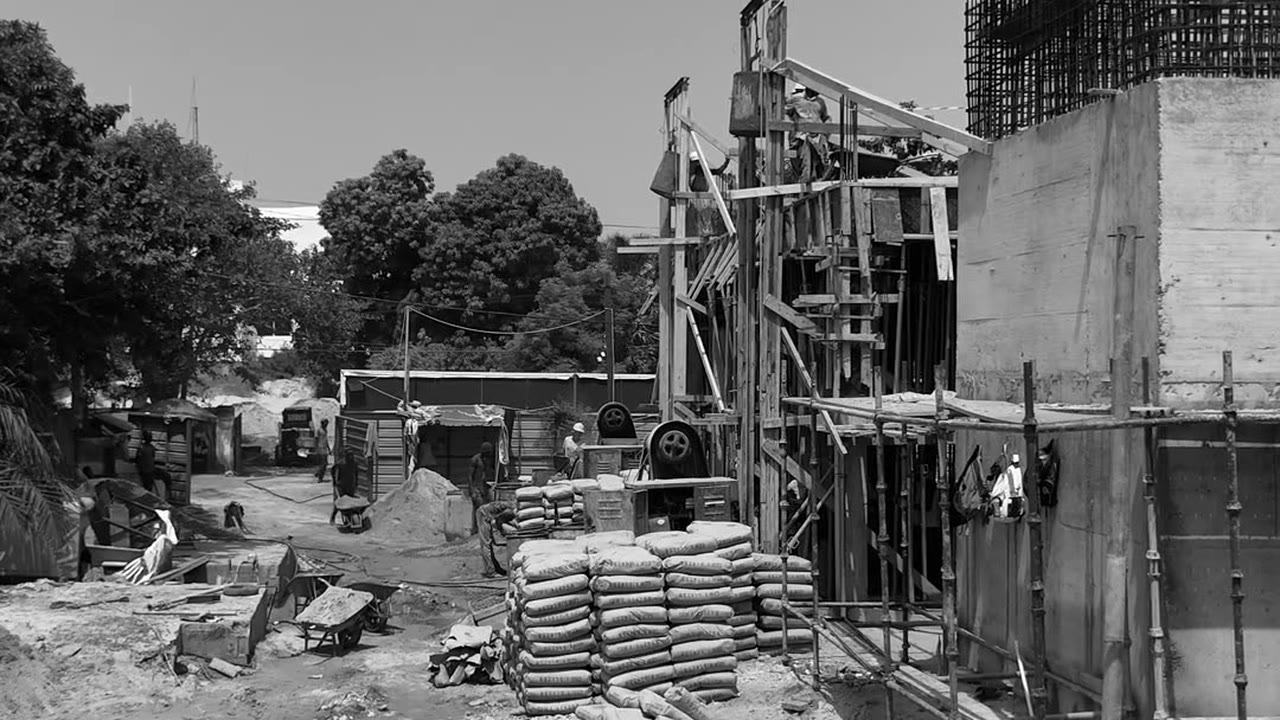
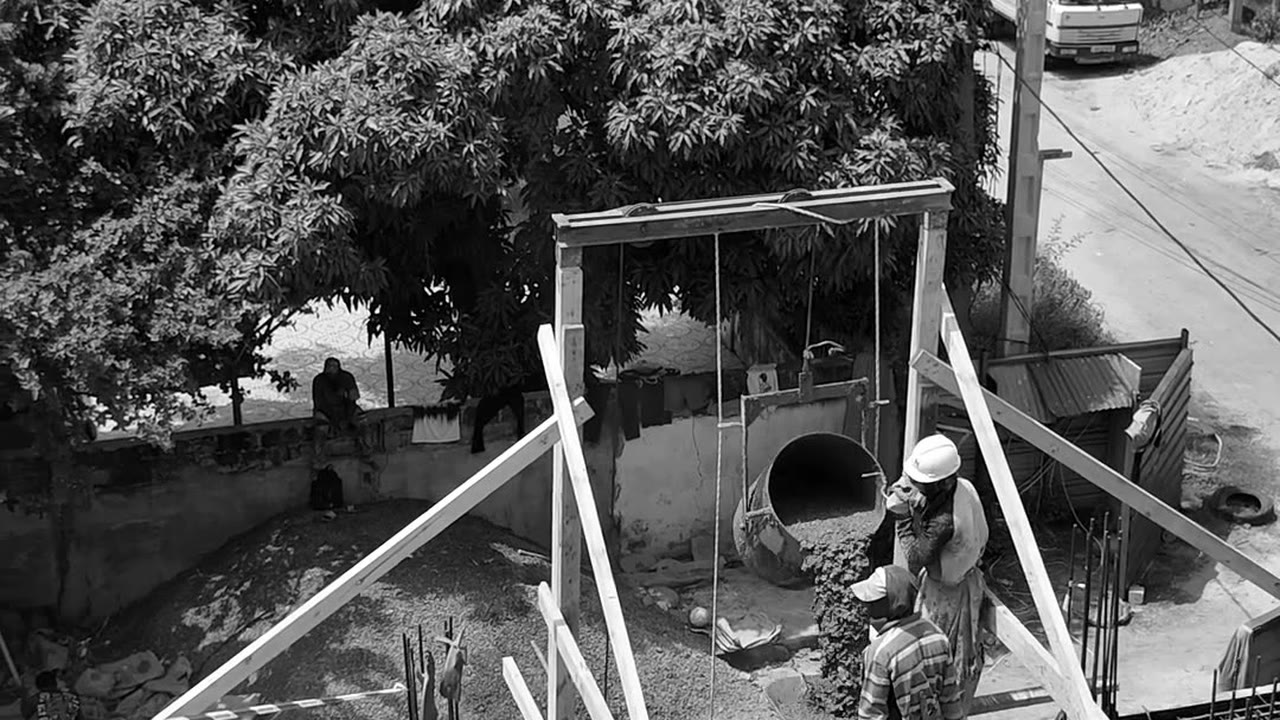
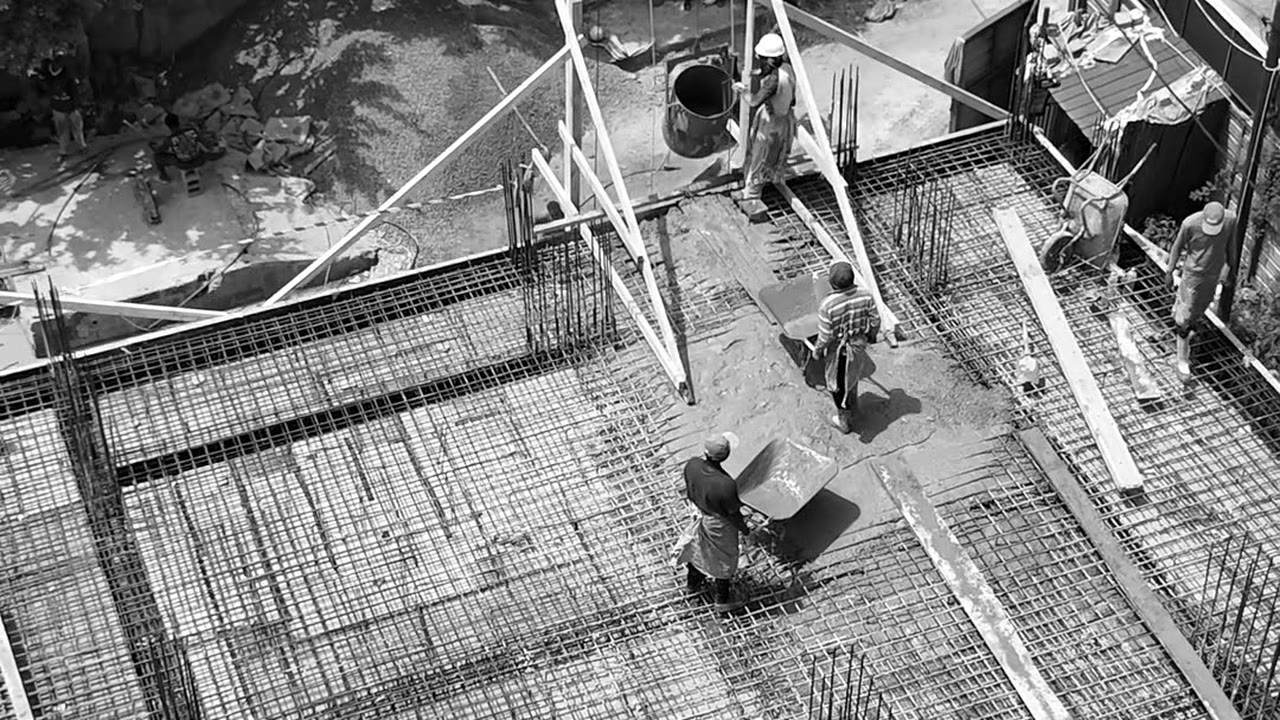
Neither figure applies, for the length of the build, to a property bought off-plan. There is no rental income to collect and no realised appreciation to count until construction finishes and the unit is handed over. Everything in the meantime rests on whether the building is progressing the way the developer says it is, which is why dated, verifiable, on-site progress evidence matters more for an off-plan purchase than a quoted future yield does.
Real UK costs beyond the deposit
The deposit is the headline number, but it is not the only cost. On a 300,000 pound property, a 25 percent deposit is 75,000 pounds. Since 31 October 2024, an additional stamp duty rate applies to a second property or an investment purchase, taking the stamp duty bill on that same 300,000 pound purchase to 17,500 pounds, versus 2,500 pounds for a sole residence, according to HomeOwners Alliance. A RICS Level 2 survey, which checks a property's structural condition before you commit to buying it, typically costs several hundred pounds on top of that. None of those three costs appear in a simple "25 percent deposit" headline, and together they can add tens of thousands of pounds to the capital a buy-to-let purchase actually requires.
Starting with less capital
If tens of thousands of pounds is not realistic yet, REITs and crowdfunding platforms are the two routes built for that. A REIT share trading under 100 dollars gives you exposure to a diversified, professionally managed portfolio without taking on a mortgage, a tenant, or a renovation. A crowdfunding platform asking for 1 to 5,000 dollars lets you back one specific project instead of a diversified portfolio, usually with less liquidity than a REIT share, since your money is tied to that project until it is sold, refinanced, or completed.
Off-plan purchases sit in between. They usually ask for a reservation deposit followed by staged payments tied to construction milestones, rather than the full price at once, which spreads the cash outlay over the build period even though the total capital required by completion is comparable to buying a finished home outright. Finished home or off-plan: the real trade-off sets out what changes, and what does not, once the building is actually complete.
The route most guides barely cover
Direct, off-plan ownership of one specific, identifiable unit gets the thinnest treatment across the ranked guides for this topic, even though it is one of the five ways HomeOwners Alliance itself lists under "ways of investing in property." Griffin Funding's six-route list omits it entirely, covering buy-to-let, flipping, REITs, crowdfunding, house hacking and short-term rentals in far more depth than it gives to buying off-plan or overseas. RW Invest's guide devotes three sentences to buying property abroad, naming only "use a bank that operates in the country" and "get expert advice," with no process for checking what a specific developer is actually building. The same guide hands the due diligence work on a specific opportunity to a paid property investment company rather than teaching a reader to do it directly.
A beginner does not need a paid consultancy to run the basic checks. Ask for dated, on-site construction photos rather than marketing renders alone. Confirm who holds legal title to the land and the unit during construction. Understand the staged payment schedule and what happens if a milestone slips. Real estate investing and overseas property investing both go further into the specific checks for pooled funds and cross-border purchases, respectively.
Choosing your first route
Match the route to your actual constraints, not the route's marketing. If your capital is under 5,000 dollars and you want liquidity, a REIT is the closest fit. If you have 1,000 to 5,000 dollars and are comfortable backing one named project for several years, a crowdfunding platform fits. If you have tens of thousands of pounds, are willing to manage tenants or a renovation directly, and want the potential for a higher net yield, buy-to-let, flipping or a house in multiple occupation fit, in roughly that order of management intensity. If you are drawn to an off-plan or overseas purchase, treat the construction evidence and the title structure as the two checks that matter most, since those are the two that the ranked guides for this topic skip or outsource.
The developer building Platinum Tower at Cape Point, Gambia, publishes dated, on-site construction photos for exactly this reason: a beginner evaluating an off-plan unit should be able to verify construction progress directly, rather than take a renders-only brochure on trust.